What this checkedNew York’s statewide freeze, 15 states weighing restrictions, and the Sep 14 additions (Pennsylvania’s 25MW order, New York’s 50MW threshold, Louisiana PSC on Hyperion, Bessent’s “D-minus”).
What it did nota moratorium delays groundbreaking, not demand, and the tracker cannot say which projects actually slip.
Watch nextNew York’s S10642 signature or veto, the ESD framework, and the Nov 3 midterms where data centers and power bills are a live issue.
Last checked: September 14, 2026 (see “What Changed Since September 1” below). Policy status changes fast in this area; always confirm against the primary sources linked below.
What a Data Center Moratorium Is, and Why It Suddenly Matters
A data center moratorium is a temporary government freeze on approving or permitting new data center construction. Until last year this was a niche zoning topic. In 2026 it became a statewide policy tool and a federal legislative proposal: on July 14, 2026, New York Governor Kathy Hochul signed Executive Order 62, the first statewide moratorium on new hyperscale data centers in the United States – a freeze of up to one year while the state writes environmental standards.
According to the National Conference of State Legislatures, fifteen states are now considering bans or moratoriums of their own – most still bills, not law. In Washington, an AI Data Center Moratorium Act has been introduced in both chambers.
If you hold AI, semiconductor or power stocks, this is not a local news story. It is a supply-chain story. One of the binding constraints in the AI buildout is no longer just chips; it is land, power, permitting and interconnection – and a moratorium sits directly on top of the last two.
The 2026 Data Center Moratorium Map
Statewide and federal-level actions, all verifiable from primary sources. Note the status column – among the measures tracked here, New York is the only statewide moratorium currently in effect:
| Measure – what it would do | Status (2026-09-14) |
|---|---|
| New York EO 62: statewide freeze on new data centers of 50 MW or more until the Department of Public Service finishes a Generic Environmental Impact Statement (the state frames this as up to one year) | IN EFFECT (signed Jul 14, 2026) |
| New York S10642 / A11560 (Responsible Data Center Development Act): one-year statutory moratorium passed by both chambers on Jun 5, 2026 | PASSED LEGISLATURE, awaiting governor (several law firms expect a veto now that EO 62 exists) |
| Delaware SB 353: would pause permits for data centers over 100 MW until Jan 2027 | INTRODUCED (in Senate committee) |
| Maine LD 307: would have paused data centers over 20 MW until Nov 2027 | VETOED (governor, Apr 24, 2026; override failed) |
| Vermont S 205: would pause data centers until 2030 with impact study | INTRODUCED (Senate Finance) |
| Pennsylvania SB 1359 / HB 2533: 3-year moratorium plus impact studies | INTRODUCED |
| Pennsylvania EO 2026-05 (GRID Requirements): not a moratorium, but state permits for data centers above 25 MW peak demand now wait for every local approval, and non-signers of the GRID consent order lose fast-track review and state support | IN EFFECT (signed Aug 18, 2026) |
| Virginia HB 1515: no final approvals until pending interconnection requests are worked through, or until Jul 2028 | CONTINUED to 2027 session |
| Federal AI Data Center Moratorium Act (S.4214, introduced Mar 25, 2026; House version H.R.9442, Jun 24, 2026): would halt new AI data center construction until federal AI rules exist | INTRODUCED |
NCSL’s tracker (updated Jul 1, 2026) counts 15 states considering some form of restriction. One independent tracker counted more than 200 local-level pauses or restrictions as of August 2026 – its definition includes county and city actions, and should not be read as 200 enacted statewide moratoriums.
Below the state level, the picture is denser: county and city boards have been pausing projects one hearing at a time. The reason is not hard to find. Gallup polling from March 2026 found 71% of Americans oppose an AI data center being built in their local area – 48% strongly. Opposition at that level is bipartisan, and elected officials act on it.
What Changed Since September 1
Four things moved in the two weeks after this article was first published, and together they sharpen the same point: the constraint is shifting from “will it be approved” to “on whose terms, and who pays for the power”.
Pennsylvania chose standards over a freeze. On August 18, 2026 Governor Josh Shapiro signed Executive Order 2026-05. It is not a moratorium. Developers of data centers above 25 MW of peak demand can sign a consent order under the GRID Requirements (pay the full cost of the electricity infrastructure they trigger, water conservation, transparency and community engagement) and get normal permit review once local approvals are in hand; those who refuse must complete every local approval and every state permit review before anything is issued, and lose fast-track status. The state’s own count in the release: more than 100 projects in public databases, 58 formally engaged with the environmental agency, 15 with permit applications, 5 with all first-phase permits. Shapiro’s line was blunt: “If you can’t agree to our strict requirements and get the community to say yes, you’re not getting Commonwealth support either.” For the investor lens above, this is one of the largest PJM states telling developers that grid cost allocation, not zoning, is the gate.
New York’s freeze has a number now, and a second track. The text of EO 62 covers facilities that “consume or can consume 50 megawatts of energy or more” and runs until the Department of Public Service delivers the final Generic Environmental Impact Statement, with no fixed end date. The separate legislative moratorium (S10642) passed both chambers on June 5 and still sits with the governor; the law firms tracking it expect a veto now that the executive order exists. Empire State Development published only a policy outline of its Community Investment Framework on July 14 and promised the full framework by mid-September, so the terms under which New York projects resume are still being written as this update goes out.
Louisiana went the other way. On August 13, 2026 the Louisiana Public Service Commission voted 3-1 to overturn an administrative law judge’s order that would have forced Meta to disclose how it calculated the job and electricity projections for its roughly 5 GW Hyperion campus, while Entergy’s proposal for additional gas units to serve it moves ahead. A PSC consultant’s June analysis put the potential impact on Entergy Louisiana bills at $8 to $13 per month on average. The same week New York was holding permits, a large-load state was fast-tracking generation and keeping the customer’s numbers private. Permitting risk is regional, and the map above should be read that way.
Washington noticed the backlash. On September 2, 2026, speaking to the Charlotte Economics Club, Treasury Secretary Scott Bessent graded the AI industry’s job of explaining data centers to Americans “on a curve, a D-minus”, saying the industry “has done a terrible job of explaining themselves” on energy and water (Bloomberg, via Yahoo Finance). Separately, Data Center Watch’s first-quarter report counted at least 75 projects worth roughly $130 billion blocked or delayed in January to March 2026 alone, about the scale of all of 2025; the group does not publish how it values projects, so treat it as a tracker estimate rather than an audited figure. Between an administration that wants the build-out and a public that increasingly does not want it next door, the midterm election on November 3 is the next date that can move the map.
Why the Backlash Has Real Numbers Behind It
Two data points do most of the work.
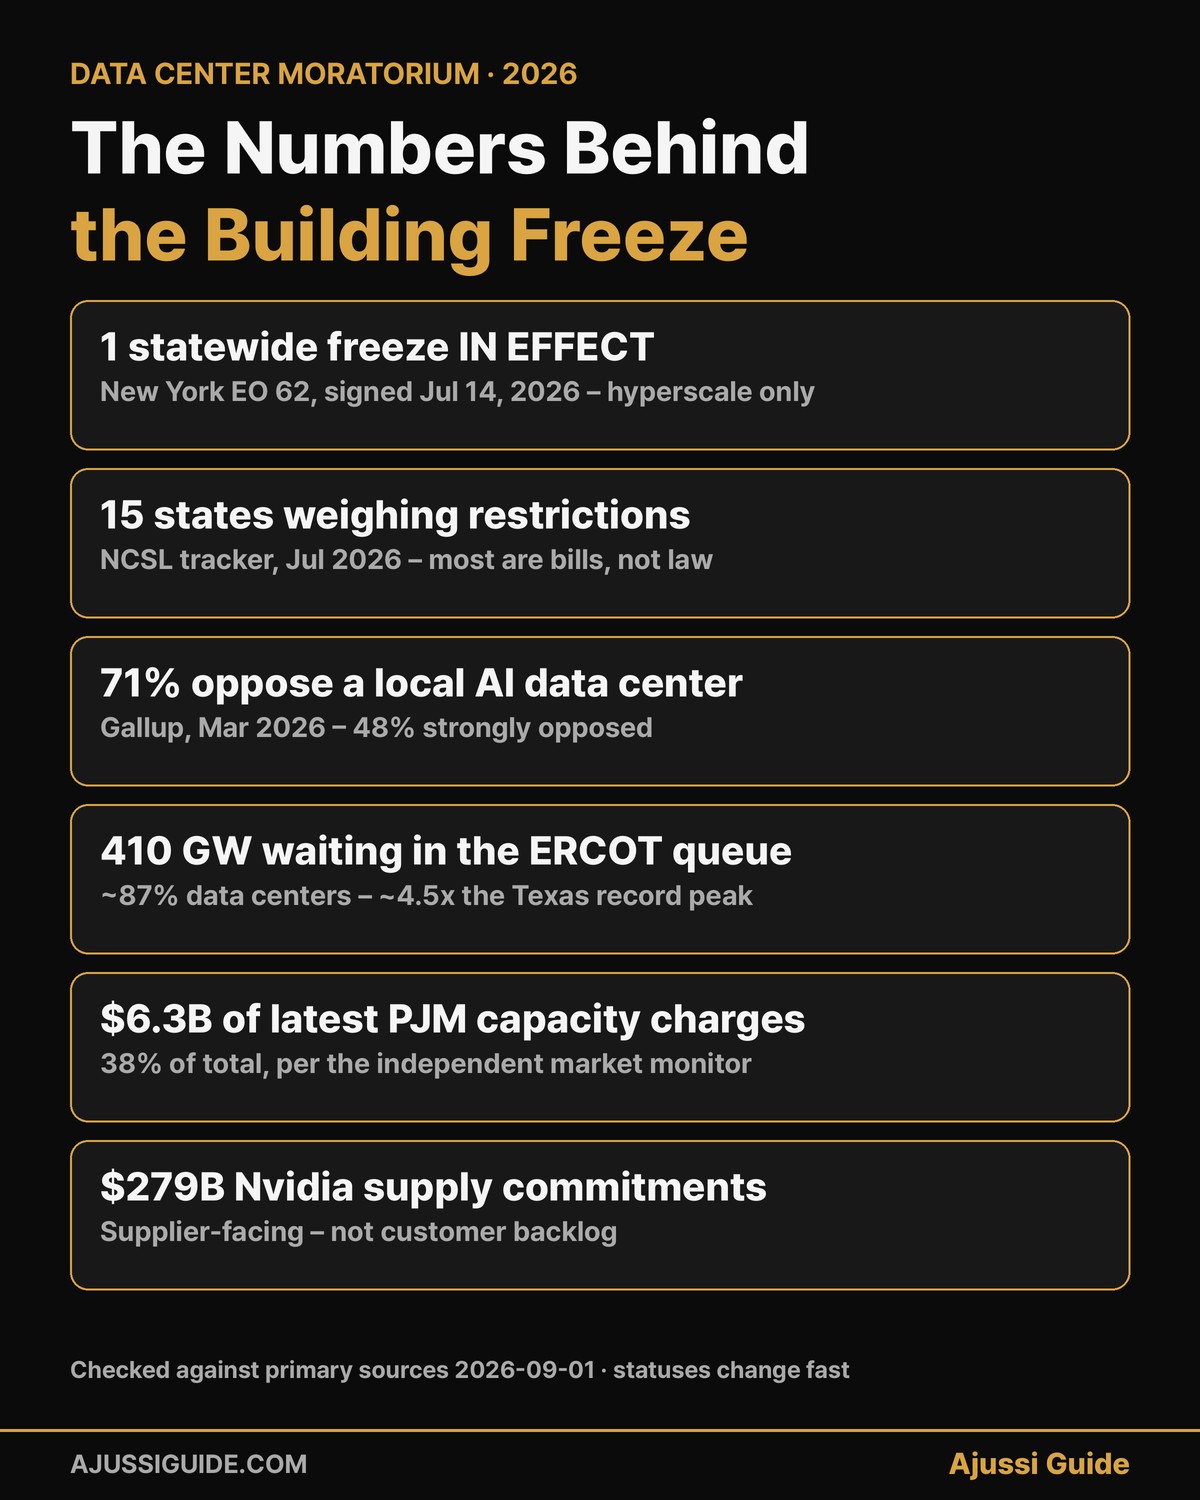
First, electricity bills. PJM’s independent market monitor estimated in July 2026 that data centers accounted for $6.3 billion of the $16.4 billion in charges from the latest capacity auction – 38% – and roughly $29.4 billion of $63.6 billion across the last four auctions.
Capacity charges can flow through to retail rates depending on utility and state rate design, which is why “data centers raised my electric bill” moved from claim to documented complaint in PJM states.
Second, the queue itself. ERCOT told Texas lawmakers in April 2026 that its large-load interconnection queue had reached roughly 410 GW of requests – about 87% of it data centers. For scale, that is about 4.5 times ERCOT’s record hourly peak demand, though queue requests are not the same as load that will actually connect. A queue like that cannot be built as requested; it has to be rationed. Rationing is done by regulators, utilities and zoning boards – not by chip companies.
The Investor Lens: Backlog Is Not Groundbreaking
Here is the framing I find most useful as a self-directed investor. Nvidia’s latest quarter (Q2 FY2027, reported late August 2026) showed $96.2 billion in revenue and $279 billion in supply commitments, up from $119 billion a quarter earlier. That $279 billion is not customer backlog – it is Nvidia’s supplier-facing supply-and-capacity commitment stack, a measure of how much future infrastructure the company is preparing to support.
The same 10-Q notes that some of those commitments can be canceled or rescheduled, and that land, power and shell availability can affect the timing of future revenue. Strong AI demand does not remove the execution bottleneck: orders, supply commitments and announced campuses only become deployed compute after land, power, permits and grid connections are secured. The people who decide that timeline are county boards, state environmental agencies and grid operators.
That reframes several positions:
Chip and memory makers carry the timing risk – not a demand collapse. If moratoriums and interconnection delays slow data center completions, GPU installations slip, and with them the revenue cadence of the AI supply chain – from accelerators down to the memory stack. It does not break the demand story; it stretches it.
Already-permitted, already-connected capacity gains scarcity value. In constrained markets, a freeze on new supply can improve the relative scarcity value of existing capacity, though the effect depends on local demand and regulation – a dynamic familiar from housing under construction limits. That is the corner of the market covered in my data center ETF comparison.
The bottleneck layer can retain demand. Projects that do proceed still require grid equipment, interconnection work and on-site power. That is the territory of the transmission and distribution stocks guide and the AI power ETF comparison. And when developers route around the grid entirely, you get projects like the one in my Amazon off-grid data center teardown – off-grid designs exist precisely because interconnection is the choke point. On the generation side, the long-dated answer is new capacity itself, which is the debate in SMR stocks vs uranium stocks.
Risks to This Framing
Moratoriums are mostly temporary and mostly local. New York’s runs up to a year; several state bills may never pass – Maine’s was vetoed even after clearing the legislature – and a federal moratorium act faces long odds in this Congress. Hyperscalers are also adapting fast – siting in friendlier states, buying existing powered shells, building off-grid. It is entirely possible that 2026’s moratorium wave shows up in the data as a few quarters of slipped completions rather than a broken cycle. The opposite risk is complacency: polling this lopsided creates political pressure for additional policy proposals into the 2026 election cycle.
Frequently Asked Questions
What is a data center moratorium?
A temporary government pause on approving, permitting or building new data centers. It can be local (a county pausing rezonings), statewide (New York’s Executive Order 62 of July 14, 2026), or proposed at the federal level (the AI Data Center Moratorium Act). Most have fixed end dates or end when new standards are adopted.
Which states have a data center moratorium in 2026?
New York is the only statewide freeze actually in force, via executive order covering hyperscale projects. Everything else at the state level is a bill: Delaware, Vermont and Pennsylvania measures are in committee, Virginia’s was continued to the 2027 session, and Maine’s passed the legislature but was vetoed in April 2026. NCSL counts fifteen states considering restrictions as of July 2026, with hundreds of county- and city-level pauses underneath, per independent tracking sites.
Does a moratorium hurt Nvidia and other AI chip stocks?
Not demand – timing. Chips generate revenue when they ship into completed, powered data centers. Permitting freezes and interconnection queues push completion dates to the right, which can stretch the revenue cadence of the whole AI hardware chain even while order backlogs grow.
Who benefits from data center moratoriums?
Existing permitted and connected capacity may gain scarcity value in constrained markets. Grid equipment and on-site power suppliers can also retain demand from projects that do proceed – but a moratorium does not guarantee higher earnings for either group.
This article is for information only and is not investment advice or a recommendation on any security. Policy status was checked against primary sources on 2026-09-01 and can change quickly. Investment decisions and their results are entirely your own responsibility.